By LE Construction · Published October 6, 2026
Most remodels are paid for with some combination of savings and borrowing. Here is how the common options work. This is general information, not financial advice; a lender or financial advisor can help you compare options for your situation.
Home equity loan
A lump sum borrowed against your home’s equity, repaid with fixed payments over a set term. Good for a project with a known price. Your home secures the loan.
Home equity line of credit (HELOC)
A revolving line you draw on as needed, often with a variable rate and an interest-only draw period. Flexible for phased projects. Also secured by your home.
Cash-out refinance
Replacing your mortgage with a larger one and taking the difference in cash. Whether it makes sense depends on your current mortgage rate versus today’s rates.
Personal loan
An unsecured loan with fixed payments, typically shorter terms and higher rates than home-secured loans, but no lien on the house.
GoGreen Financing for energy upgrades
GoGreen Financing is a State of California program, run through the State Treasurer’s office, that helps homeowners finance energy upgrades through participating lenders. According to the program:
- Loans are offered with no money down, no closing costs and no lien on the property.
- Eligible measures include heat pump heating and cooling, heat pump water heaters, induction ranges, Energy Star appliances, insulation and lighting.
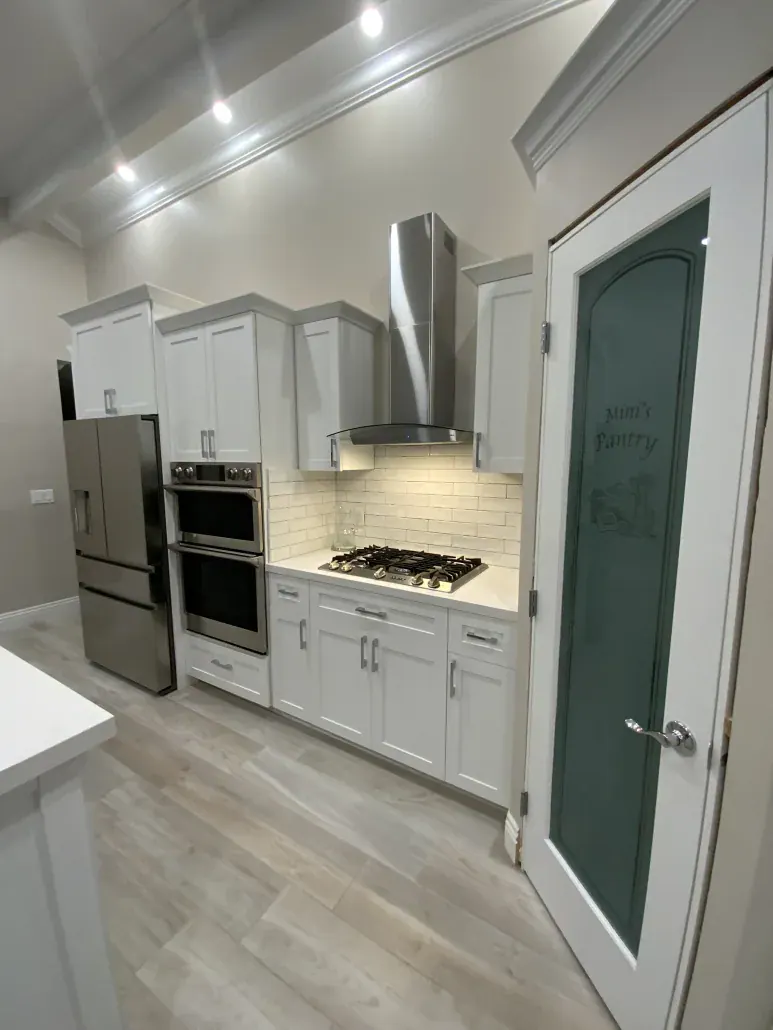
- Up to 30% of the financed amount can go toward other upgrades, such as new cabinetry.
In a remodel, the energy parts, like an induction range, LED lighting, insulation or a heat pump water heater, may qualify. LE Construction works with GoGreen Financing; the lender approves the loan and sets the terms. (Financing)
Paying your contractor
California law limits the down payment on a home improvement contract to $1,000 or 10% of the price, whichever is less, and later payments should match work completed and materials delivered. That protects you no matter how you finance.
A practical approach
- Get a written, line-item estimate.
- Identify parts that may qualify for program financing.
- Compare loan options with a lender.
- Match draws or payments to the contract’s milestone schedule.
See our cost guides and how we run a project.
Frequently asked questions
What is the difference between a home equity loan and a HELOC?
A home equity loan is a lump sum with fixed payments. A home equity line of credit (HELOC) is a revolving line you draw on as needed, often with a variable rate. Both are secured by your home.
Can GoGreen Financing cover my whole remodel?
Usually not. GoGreen is a State of California program for energy upgrades, and it allows up to 30% of the financed amount for other improvements such as cabinetry. It can cover the energy-related parts of a remodel.
How should I pay my contractor if I finance?
The same way as with cash. California limits the down payment on a home improvement contract to $1,000 or 10% of the price, whichever is less, with later payments matched to completed work.
Should I talk to a lender before getting a contractor estimate?
Either order works, but a written estimate gives the lender a real number. Many owners get an estimate first, then compare financing options.